Helping responsible lenders grow their loan books in difficult times
It’s hard to remember a time when lending was this difficult. One pressure is the impact as 1.5m people leave fixed rate mortgages this year. They’ll spend an additional £19bn on mortgage repayments in 2024. Currently with higher credit scores, these ‘near-prime’ borrowers have been a priority for credit unions looking to balance loan books…
Read MoreBetter referral for declined applicants
At the beginning of this year’s Debt Awareness Week, it was reported that 13% of adults had missed three or more credit or bill payments in the last six months. Credit unions are used to seeing this. For example, between 1 January and 18 March 2023, 29% of borrowers assessed by NestEgg’s Decision Engine had…
Read MoreData driven decisions
As we head from London to the North West to Manchester for the ABCUL conference, NestEgg has compared the data from lending decisions made in these areas. This is to help credit unions make data driven decisions. Overall, lending risk in the North West is higher than the South East (including London). Despite higher incomes…
Read MoreNestEgg joins the FCA Financial Inclusion TechSprint
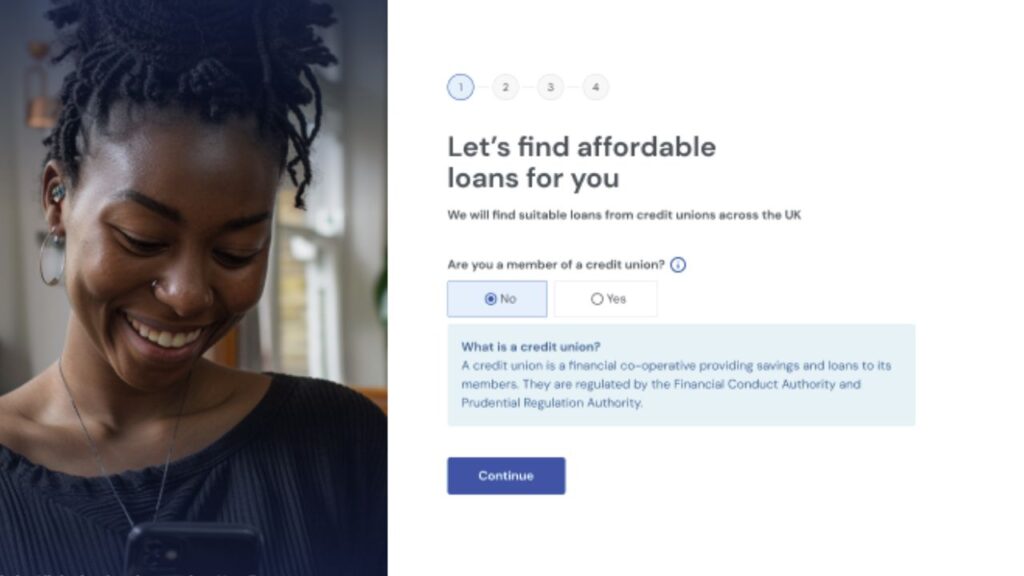
NestEgg is delighted to announce its participation in the FCA Financial Inclusion TechSprint. The TechSprint aims to utilise technology to boost the chances of loan approval and foster financial inclusion. The problem Our participation addresses two sides to the challenge. Firstly, people need help to find an alternative lender that is more likely to accept…
Read MoreWhat is a debt management plan?
Dealing with debt can be overwhelming, when it feels like there’s no clear way out. Debt Management Plans (DMPs) can help individuals pay off debts at a rate they can afford, over a longer period of time. However, they will have consequences on an individual’s ability to borrow in the future, as a ‘live’ DMP…
Read MoreWhat is an individual voluntary agreement (IVA)?
An Individual Voluntary Arrangement (IVA) is a form of debt management and alternative to bankruptcy. They are designed to help individuals who are struggling to manage their debt. How do they work? IVAs work by ‘freezing’ an individual’s debts (including interest and charges) for a fixed period of time (usually 5 – 6 years). Over…
Read More